

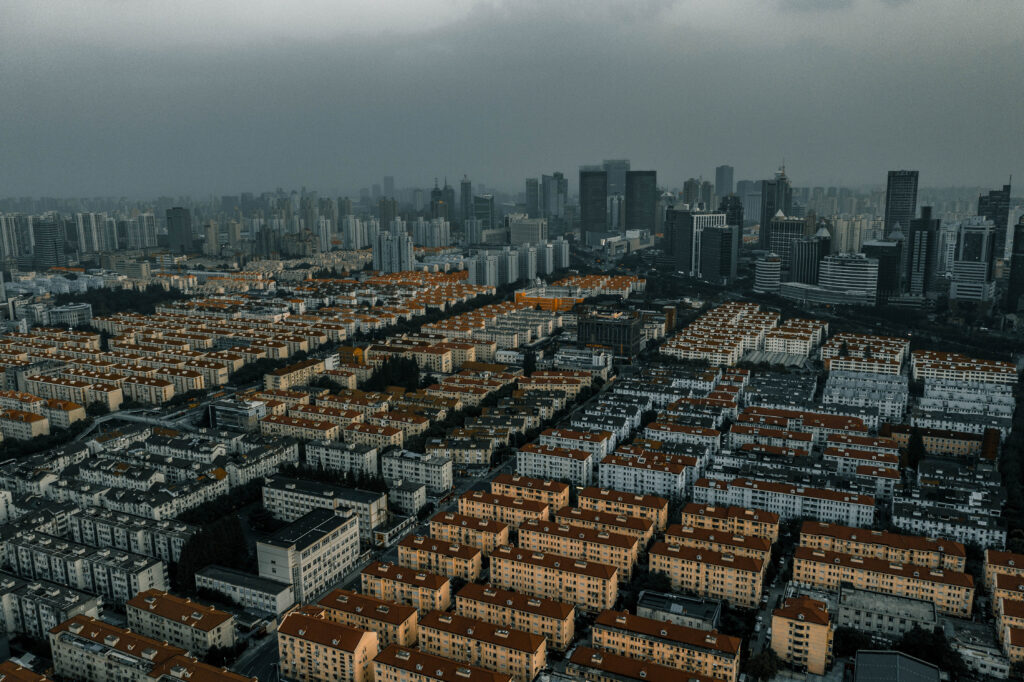
China is introducing new measures to support its property market and wider economy as growth loses momentum. The latest package combines mortgage interest subsidies for first-time homebuyers with cheaper central bank funding and additional resources for equipment and technology investment. Together, these steps show a stronger focus on supporting both household demand and investment activity.
The measures come at a sensitive point for the Chinese economy. GDP expanded 4.3% year on year between April and June, below the official full-year target range of 4.5–5%. Retail sales and fixed-asset investment have also shown weakness, while the prolonged property slowdown continues to affect domestic confidence.
Direct Support for First-Time Buyers
China’s Ministry of Finance has announced an annual mortgage interest subsidy of 1 percentage point for eligible first-time buyers. The subsidy will be available for up to five years and will cover mortgage principal of up to Rmb1mn ($149,000) per household. Eligible properties must have a gross floor area of no more than 120 square metres and a value of up to Rmb1.5mn.
The initiative is notable because it directly reduces financing costs for households. Previous efforts to stabilise the property sector have included measures aimed at developers, banks and local housing markets, but the new subsidy puts household affordability more clearly at the centre of the policy response.
Its importance may therefore extend beyond an immediate increase in property transactions. Morgan Stanley economists cited in the source argued that the policy could be particularly significant because it demonstrates Beijing’s willingness to use central fiscal resources directly to support housing demand and household balance sheets.
Why Housing Still Matters for China’s Economy
China’s property downturn has persisted for years, with new home prices continuing to decline. The consequences reach well beyond developers and homebuyers because housing is closely connected to household wealth, construction, industrial demand and local government finances. Persistent weakness can therefore influence consumer confidence and economic activity across multiple sectors.
The new mortgage subsidies seek to address one part of this problem by reducing the cost of purchasing a home. However, lower borrowing costs alone may not be enough to produce a sustained recovery. Businesses and investors will need to watch whether the policy leads to stronger transactions, stabilising prices and improved household confidence.
These indicators will also provide clues about consumer demand. If households become more confident about property values and their financial position, the impact could gradually spread beyond real estate into retail spending and other areas of domestic consumption.
Cheaper Funding for the Real Economy
Housing support is only one component of the latest policy response. The People’s Bank of China has also cut the rate on its one-year pledged supplementary lending facility by 25 basis points to 1.5%. The PSL mechanism provides lower-cost funding to policy banks, allowing them to finance investment in areas prioritised by policymakers.
The programme, introduced in 2014, will now have a broader scope that includes communications and logistics networks. According to the central bank, the lower rate is intended to strengthen incentives for policy banks to support the real economy. This could increase financing activity across infrastructure and related industrial supply chains.
The PBoC is also expanding its relending programme for equipment upgrades and technology. Its quota will increase by Rmb200bn, reaching Rmb1.4tn. This represents another channel through which policymakers are seeking to encourage capital expenditure and technological modernisation.
A Two-Sided Economic Strategy
Taken together, the measures reveal a two-sided approach. On the household side, mortgage subsidies aim to make housing more affordable and potentially strengthen confidence. On the investment side, cheaper PSL funding and a larger relending programme are designed to direct capital towards infrastructure, equipment and technology.
This approach reflects the broader challenge facing policymakers. China needs to address weakness in property and domestic demand while maintaining investment in areas that could support future productivity and industrial development. The cabinet has already called for stronger countercyclical macroeconomic adjustments, while policymakers have indicated plans to accelerate fiscal spending.
For companies operating in or trading with China, the transmission of these policies into the real economy will now be critical. Housing transactions, property prices and retail activity can indicate whether household confidence is improving, while infrastructure expenditure and industrial investment will show how effectively additional financing is reaching businesses.
The latest measures are therefore about more than cheaper mortgages. They represent an attempt to support several connected parts of the Chinese economy at the same time. How households and businesses respond will help determine the outlook for domestic demand, industrial activity and regional supply chains.